Annual Reports
Cheuk Nang (Holdings) Limited's annual reports contain management's most considered account of the business. These are the sections, passages and visual pages worth opening in the originals preserved in Sources.
Cheuk Nang (Holdings) Limited — Annual Report 2025 (year ended 30 June 2025) — FY2025 (year ended 30 June 2025)
Latest report: a HK$1,144m loss driven by a HK$915m investment-property revaluation and a HK$166m provision against development inventory. · Open the full document →
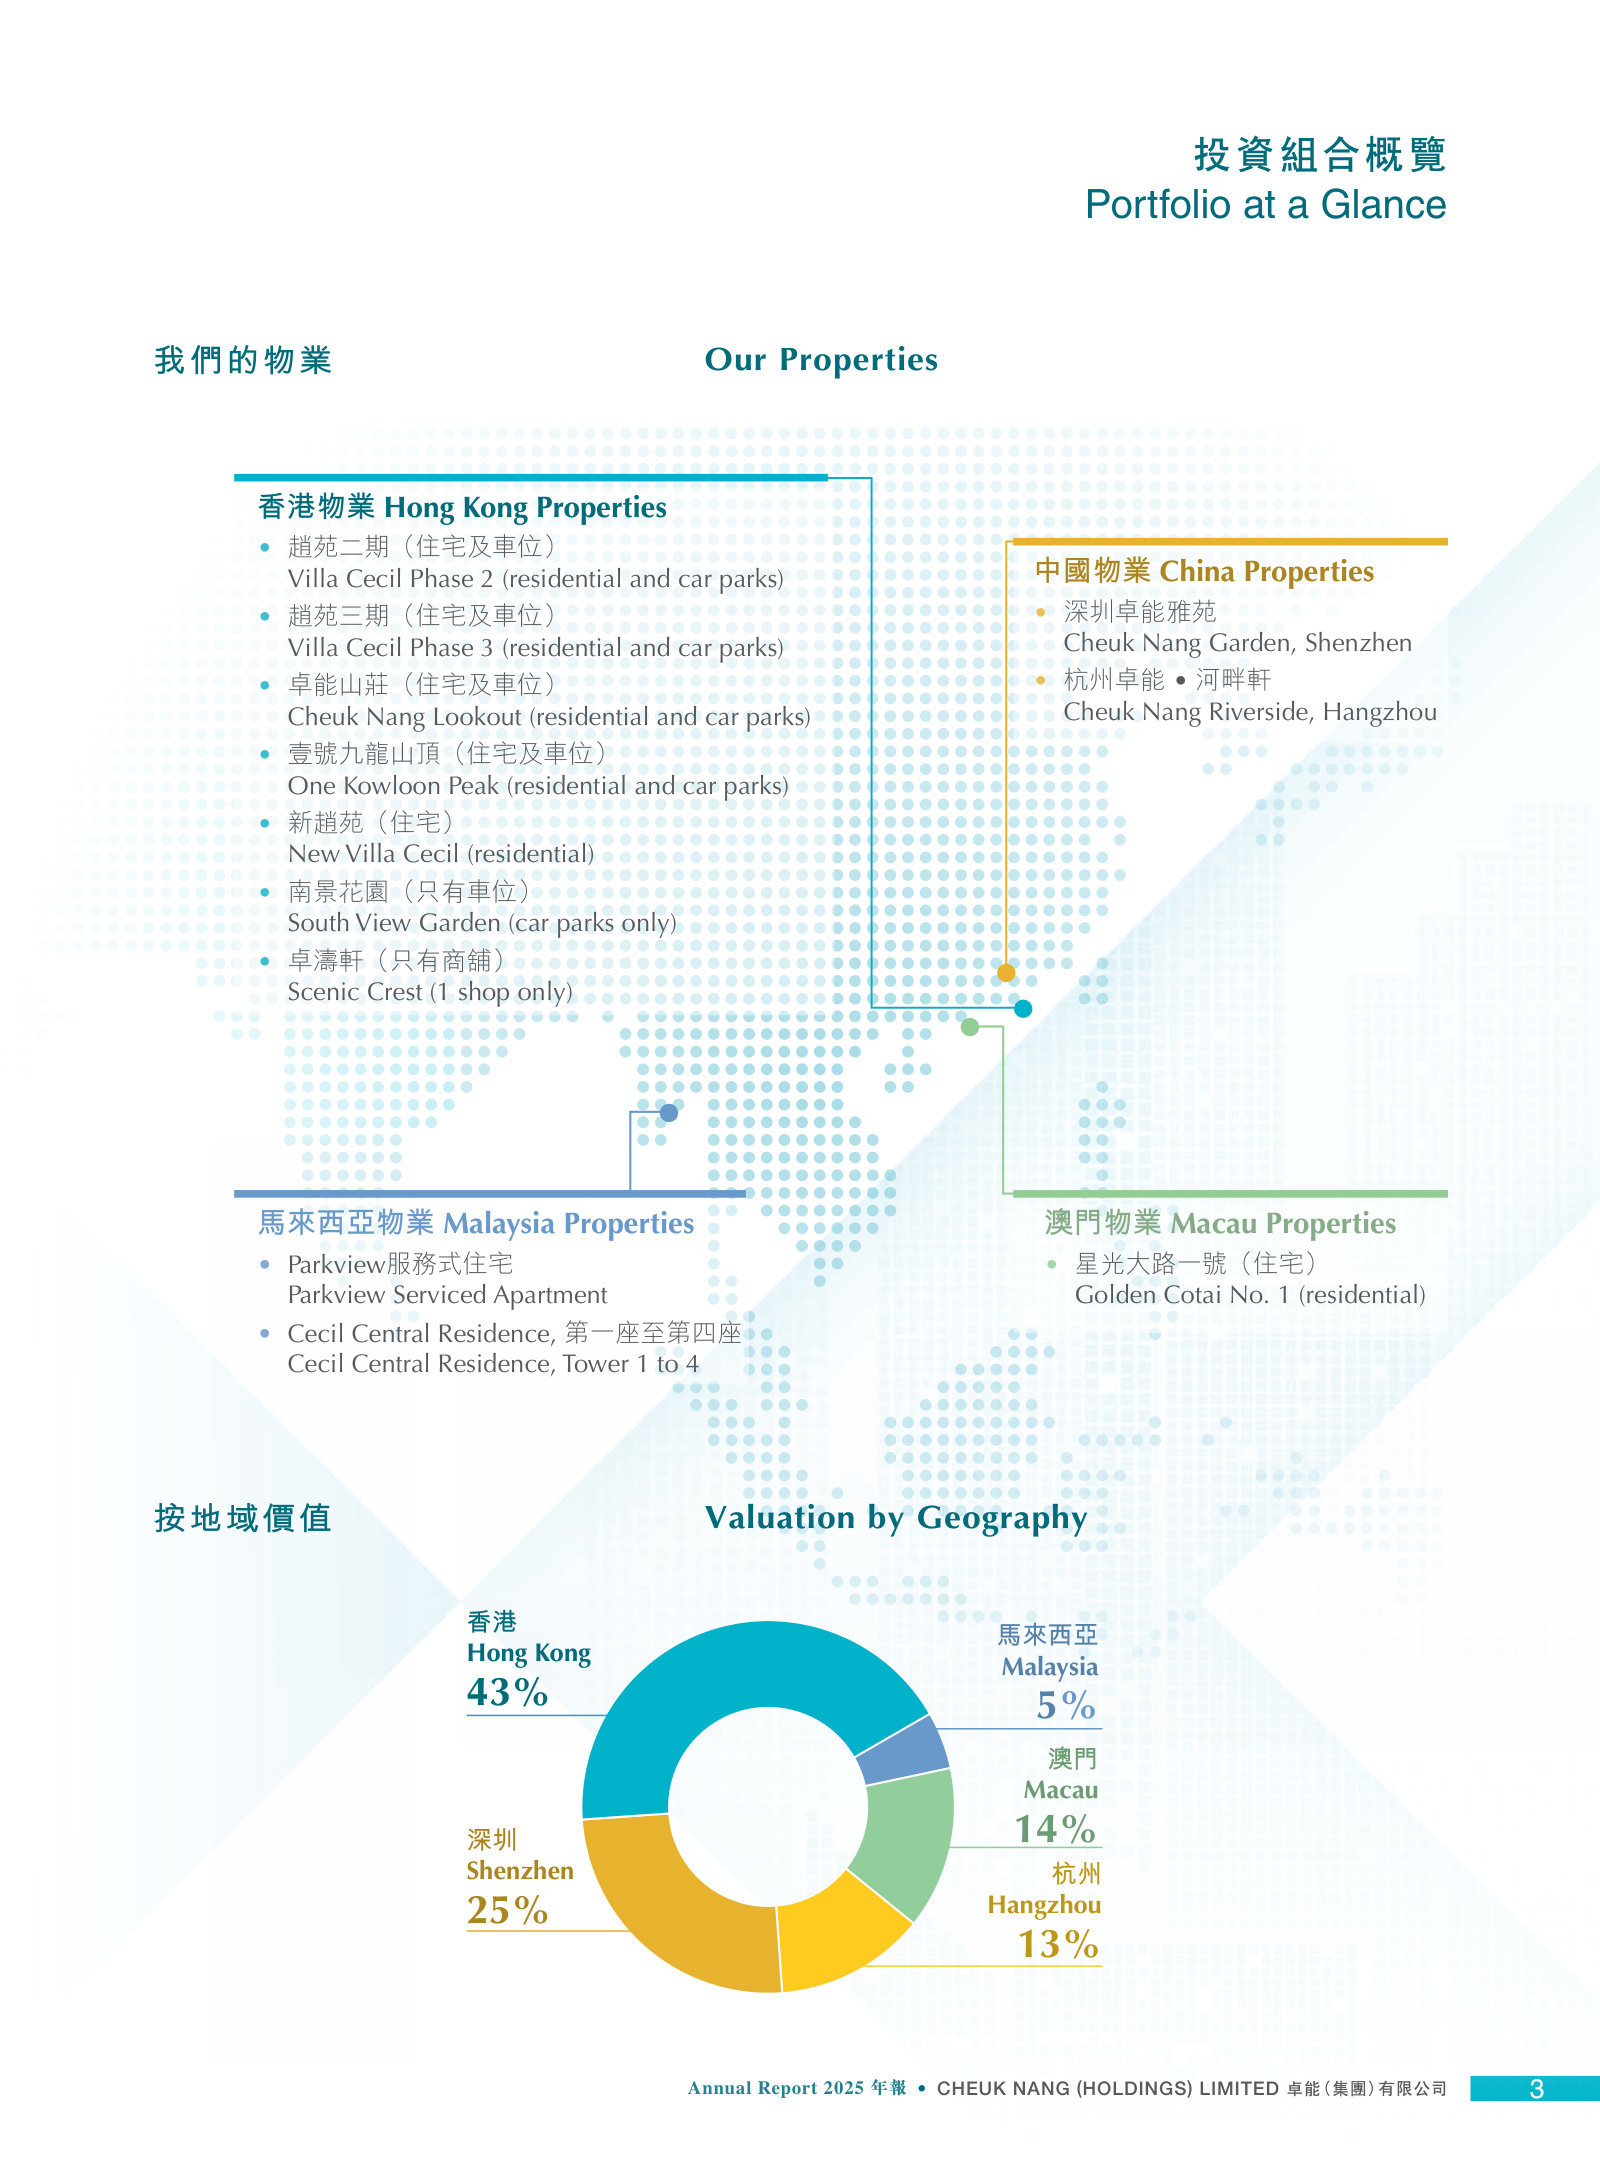
Portfolio at a Glance — p. 4 · Read the full section →
The whole portfolio on one page, with the split of value across Hong Kong, Shenzhen, Macau, Hangzhou and Malaysia.
Chairman's Statement — p. 14 · Read the full section →
Management's own account of the loss year, and of trophy assets that did not clear at the price they wanted.
Results and dividend: a HK$1,144m loss after a HK$171m profit, with the payout cut 32%.
The consolidated loss after income tax of our Group for the year ended 30 June 2025 is HK$1,144,071,000 comparing to profit after income tax of 2024: HK$171,004,000 […] The Directors resolved to recommend the payment of a final dividend of HK2.00 cents (2024: HK4.00 cents) per share […] makes a total distribution of HK4.25 cents (2024: HK6.25 cents) per share this year, which is 32% decrease when compare to last year.
p. 14 · Read in context →
Cheuk Nang Lookout: a tender for Villa Crocus drew offers, none at the price management expected.
During the year under review, a public sale by invitation to tender was launched for Villa Crocus. While we had received a few serious offers, the prices received did not match our expectations for the property, therefore over the future months we will continue to carry out asset enhancement strategies on the two villas in a concerted manner.
p. 16 · Read in context →
Management Discussion and Analysis — p. 32 · Read the full section →
Where management attributes the swing: no Hong Kong sales, a HK$915m revaluation deficit and admin costs up 412%.
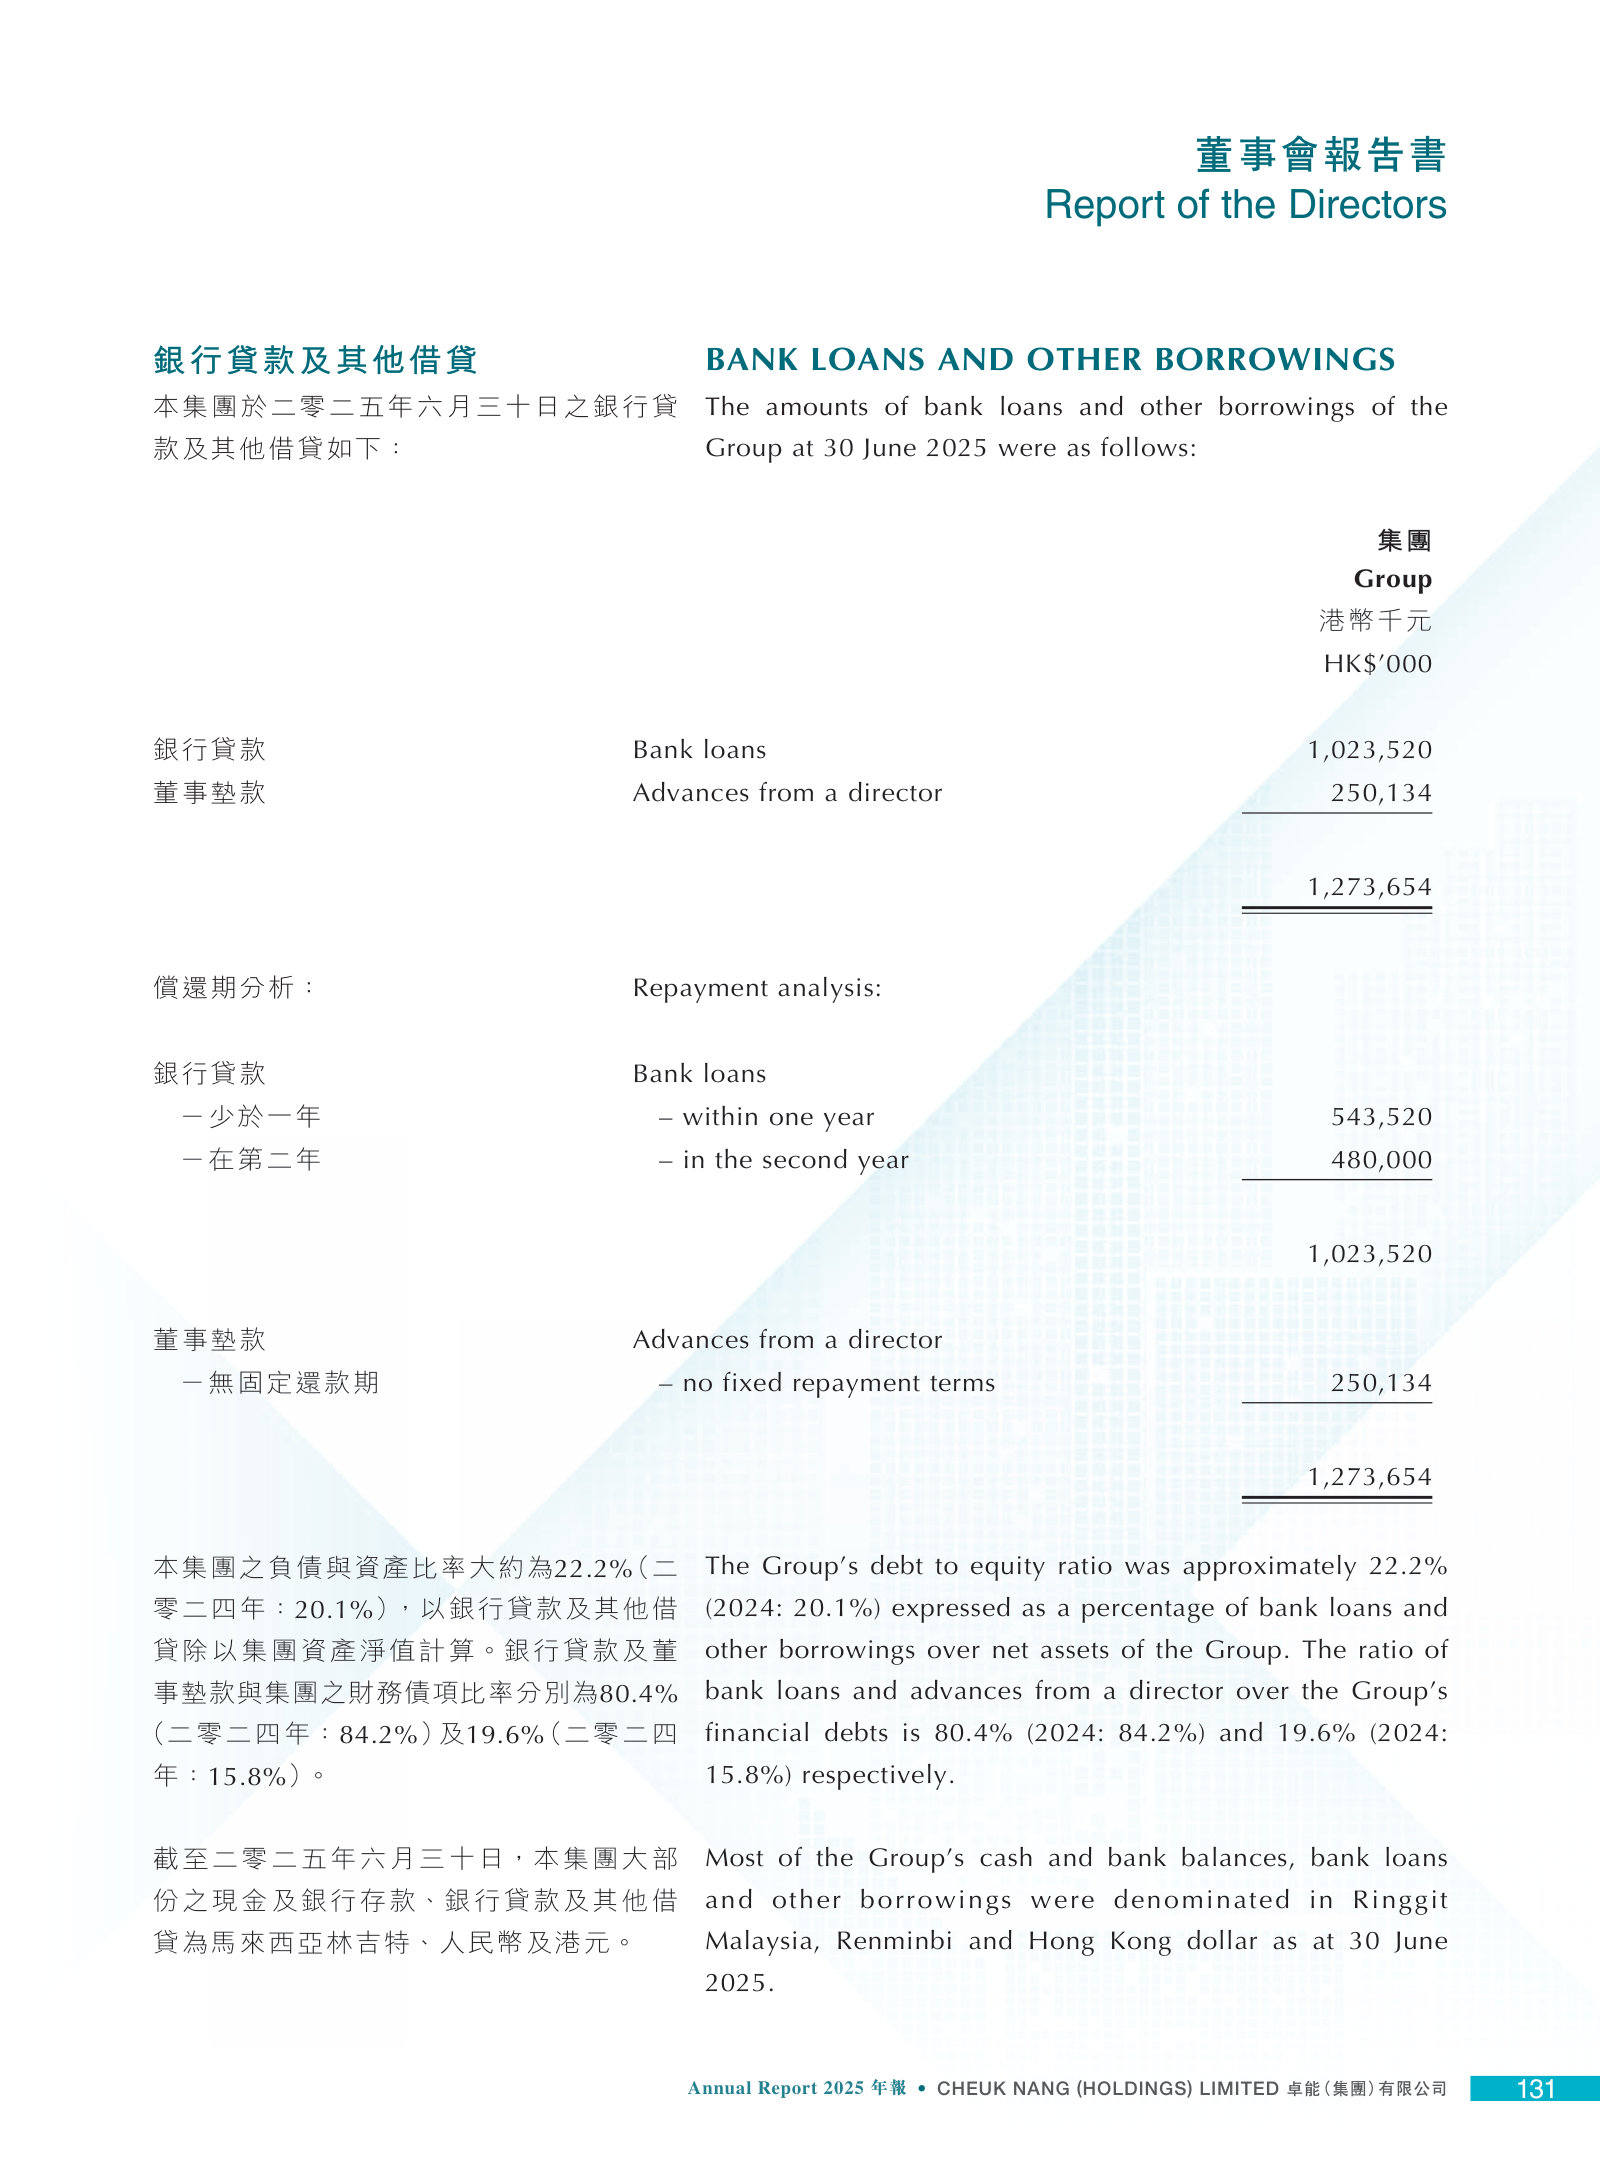
Maturity of borrowings after the repayment-on-demand clause: 62.3% of HK$1,274m falls due within one year.
Of the Group’s total bank and other borrowings HK$1,273,654,000 (2024: HK$1,343,125,000), 62.3% (2024: 100%) and 37.7% (2024: NIL) were repayable within 1 year and 1 to 2 years respectively reference to the repayment on demand clause based on scheduled repayments of the loan agreement.
p. 35 · Read in context →
Report of the Directors — p. 129 · Read the full section →
The formal statement of the business — investment holding over property development, investment and management — and of how it is funded.
Independent Auditor's Report — Key Audit Matters — p. 140 · Read the full section →
Grant Thornton names the two judgements that move the numbers most: property fair value and inventory recoverability.
KAM 1 — HK$3,683m of investment properties at fair value, with a HK$915m fair-value decrease in the year.
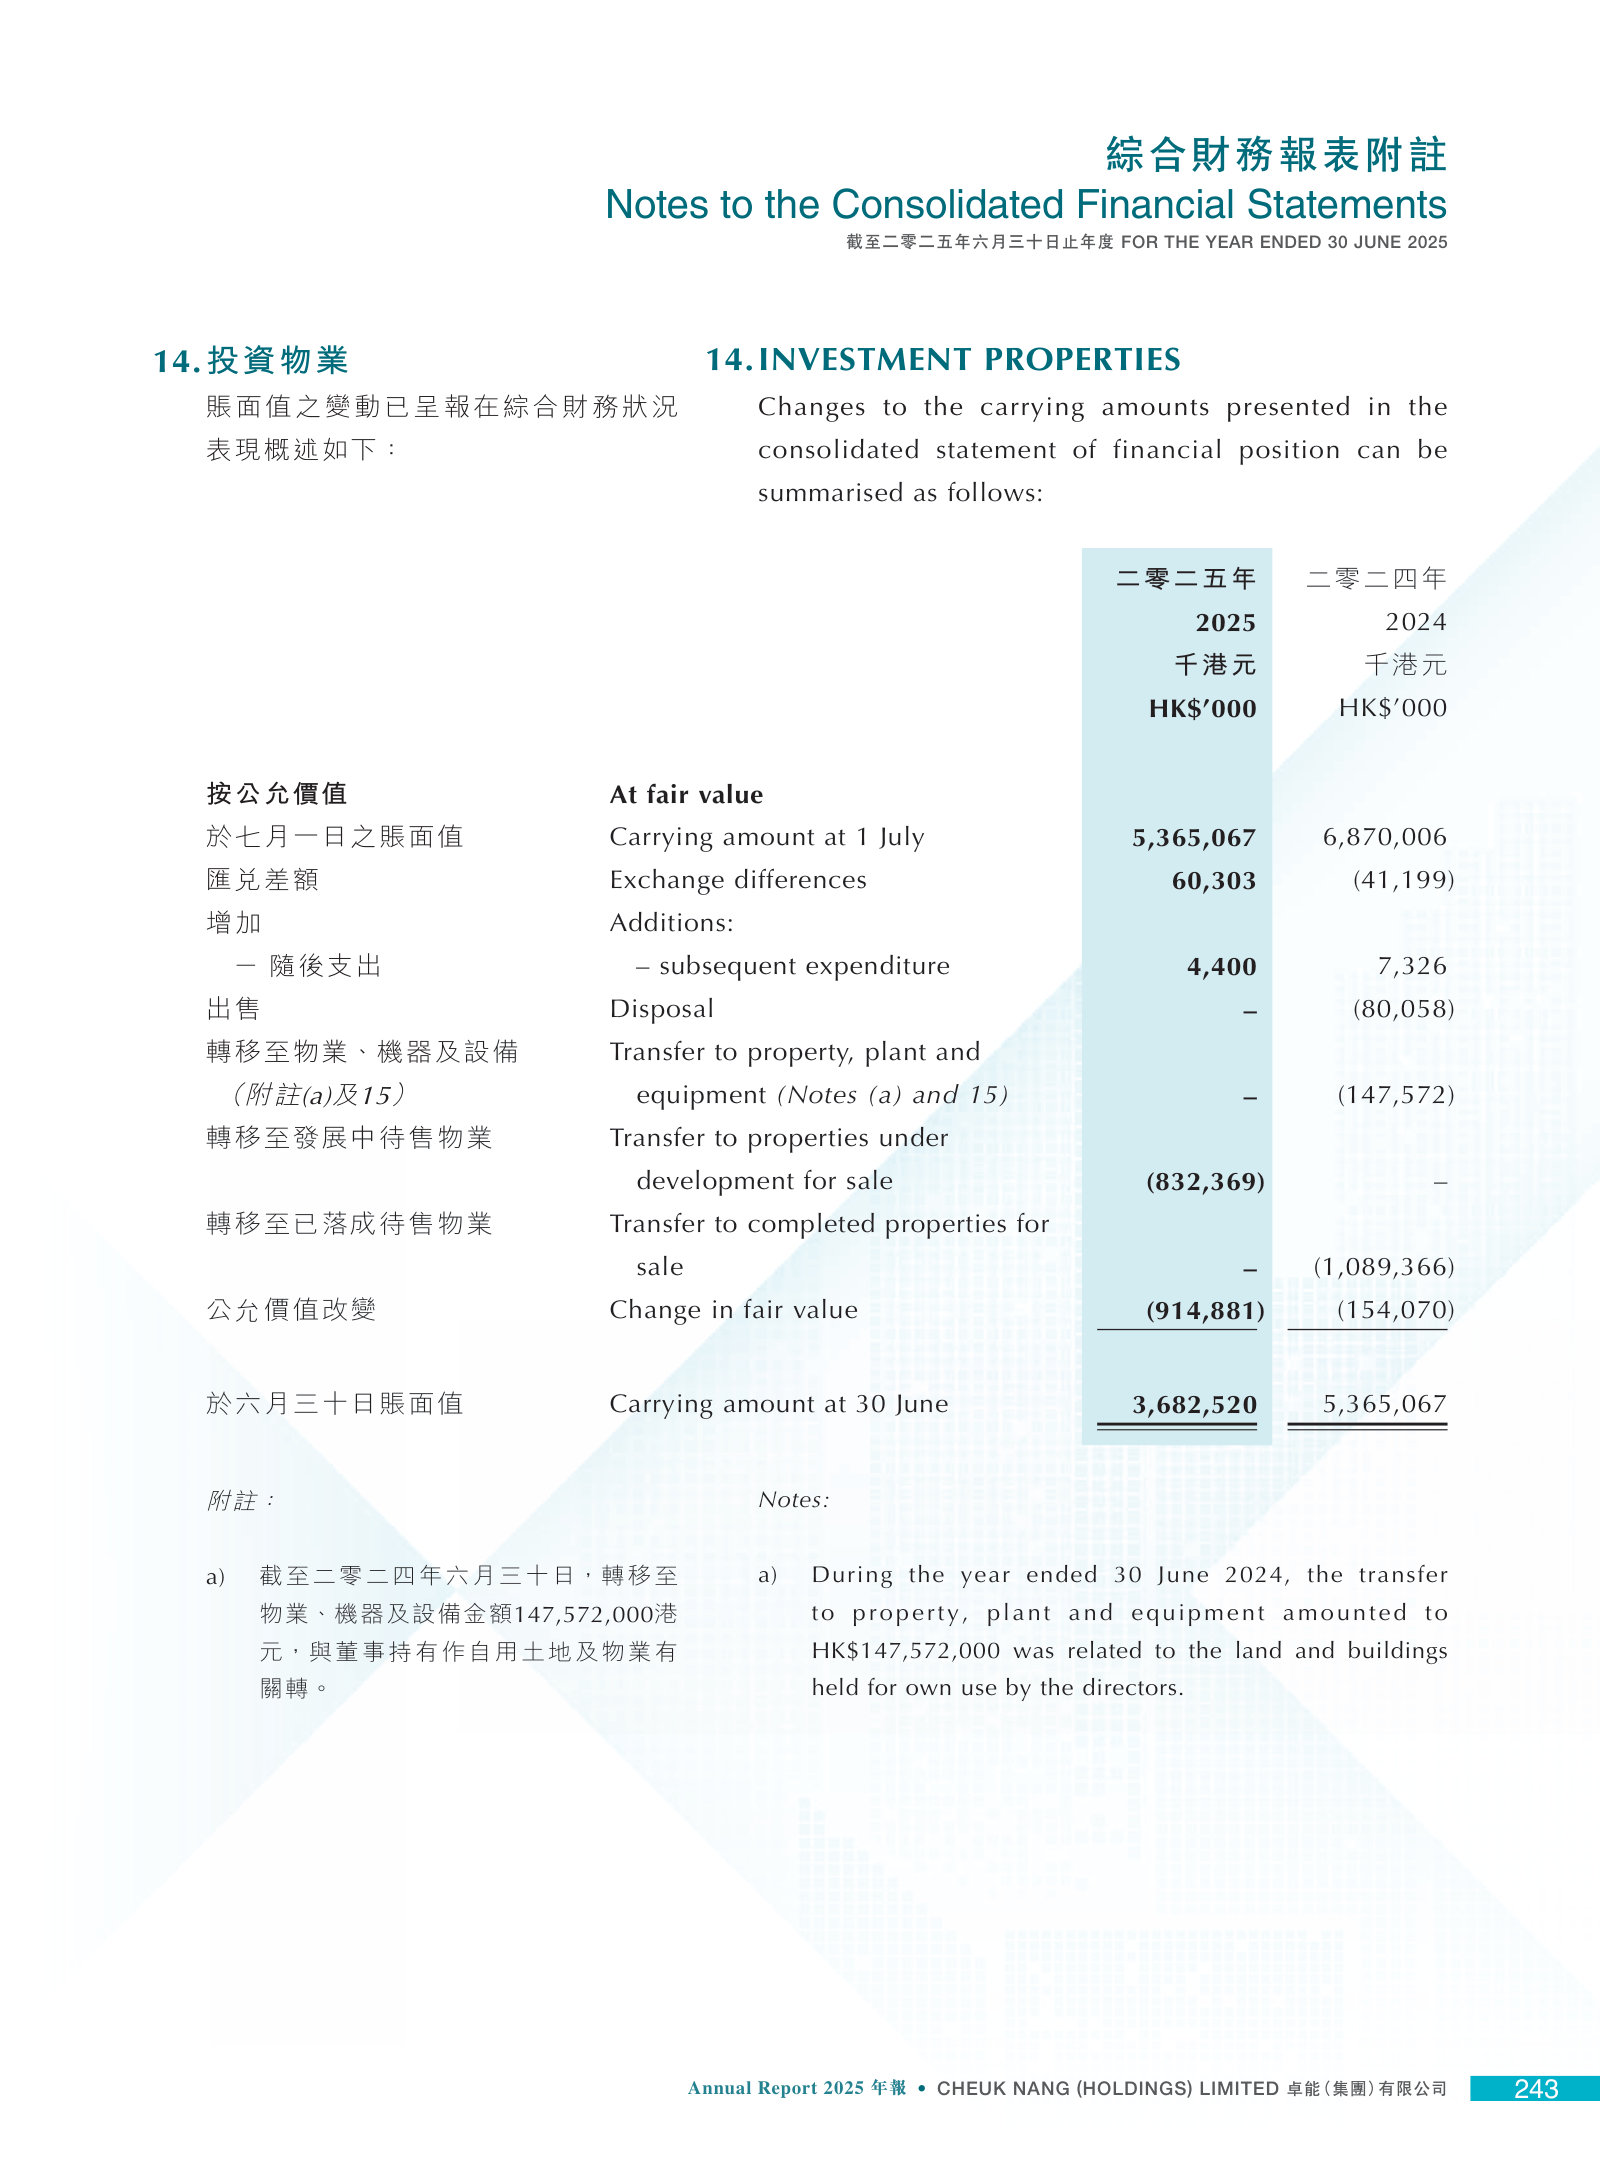
As at 30 June 2025, the Group had investment properties measured at fair value amounted to approximately HK$3,682,520,000 and a decrease in fair value of investment properties of approximately HK$914,881,000 was recognised in the consolidated statement of profit or loss for the year then ended. […] We focused on this area because the significant estimates and judgement involved in determining the property valuations warrants specific audit focus and attention on this area.
p. 142 · Read in context →
KAM 2 — HK$3,591m of properties held for sale tested against net realisable value.
As at 30 June 2025, the Group had properties held for sale amounting to approximately HK$3,590,576,000. […] Properties held for sale are stated at the lower of cost and net realisable value. Net realisable value represents the estimated selling price less estimated costs of completion and costs to be incurred in selling the property. The net realisable value was determined by the Group with reference to the valuation performed by independent qualified external valuers. Given the significant judgements and estimates used in assessing the net realisable value of properties held for sale, such assessment is considered significant to our audit.
p. 144 · Read in context →
2.5 Investment Properties (Summary of Material Accounting Policies) — p. 170 · Read the full section →
The policy that makes earnings swing with valuations rather than with trading: revaluations go straight through profit or loss.
Investment properties carried at external valuers' fair value, with every change recognised in profit or loss.
Investment properties are measured at cost on initial recognition and subsequently at fair value. Fair value is determined by external professional valuers, with sufficient experience with respect to both the location and nature of the investment property. […] Gains or losses arising from either changes in the fair value or the sale of an investment property are included in profit or loss in the period in which they arise.
p. 171 · Read in context →
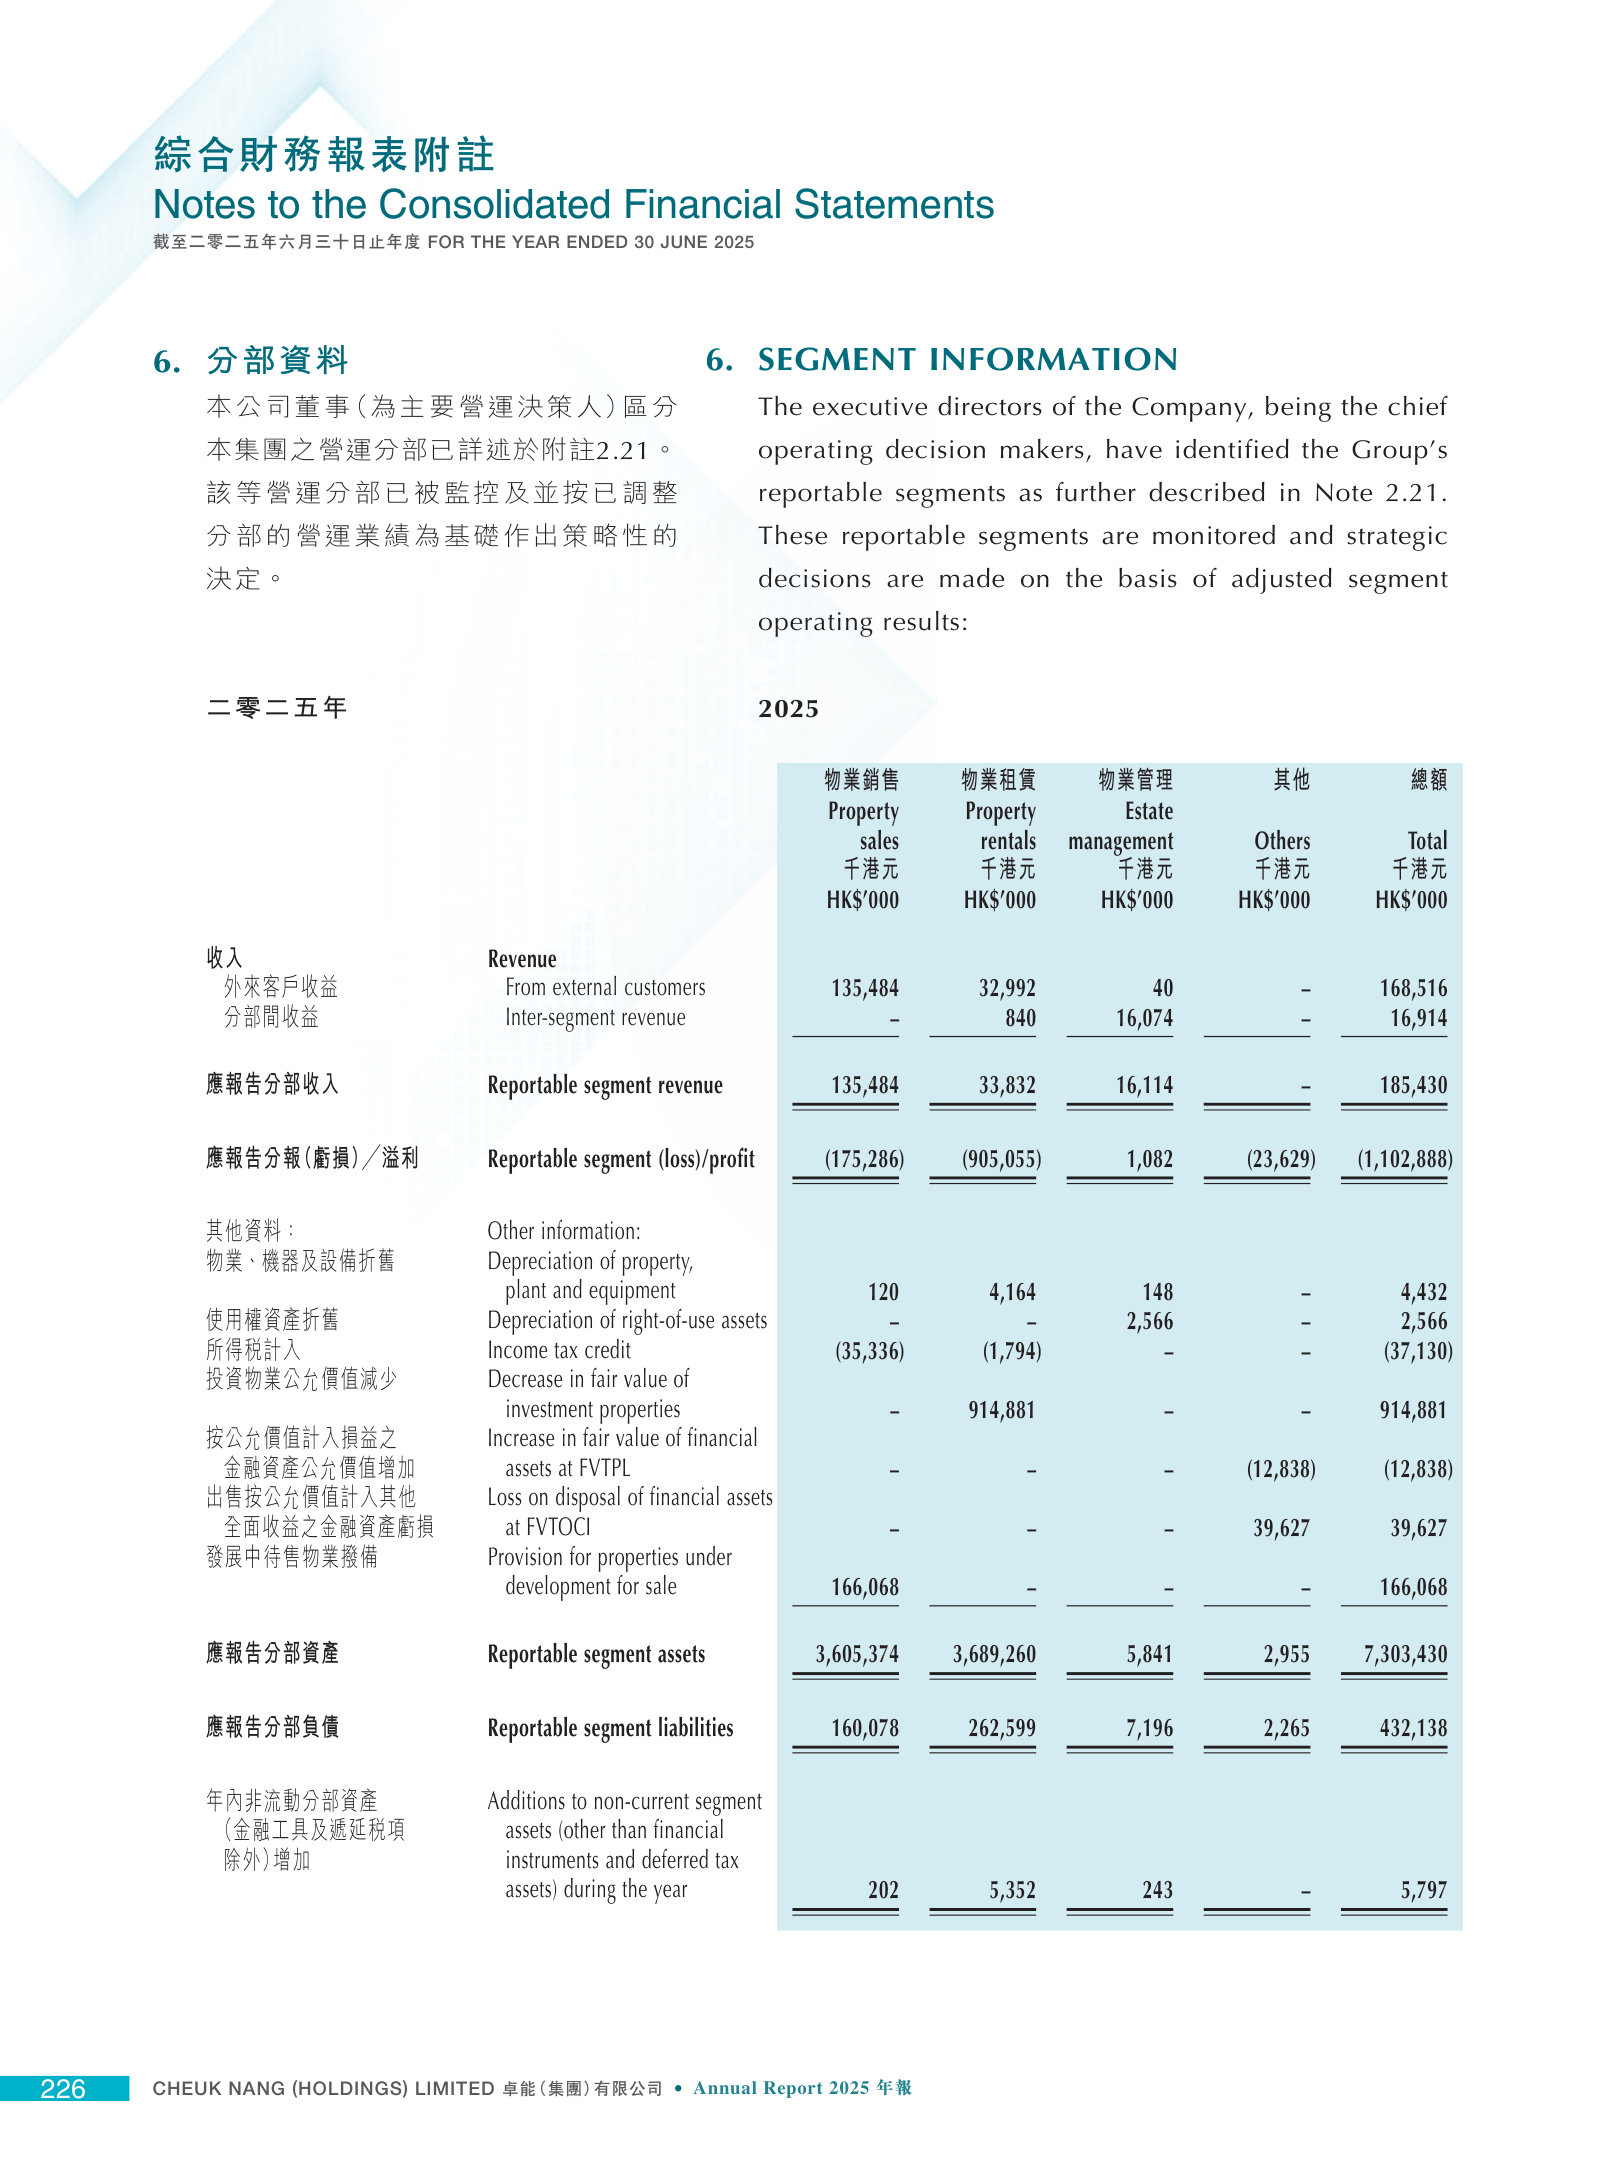
6. Segment Information — p. 227 · Read the full section →
The audited split of a business with two engines: lumpy property sales and a small, steady rental book.
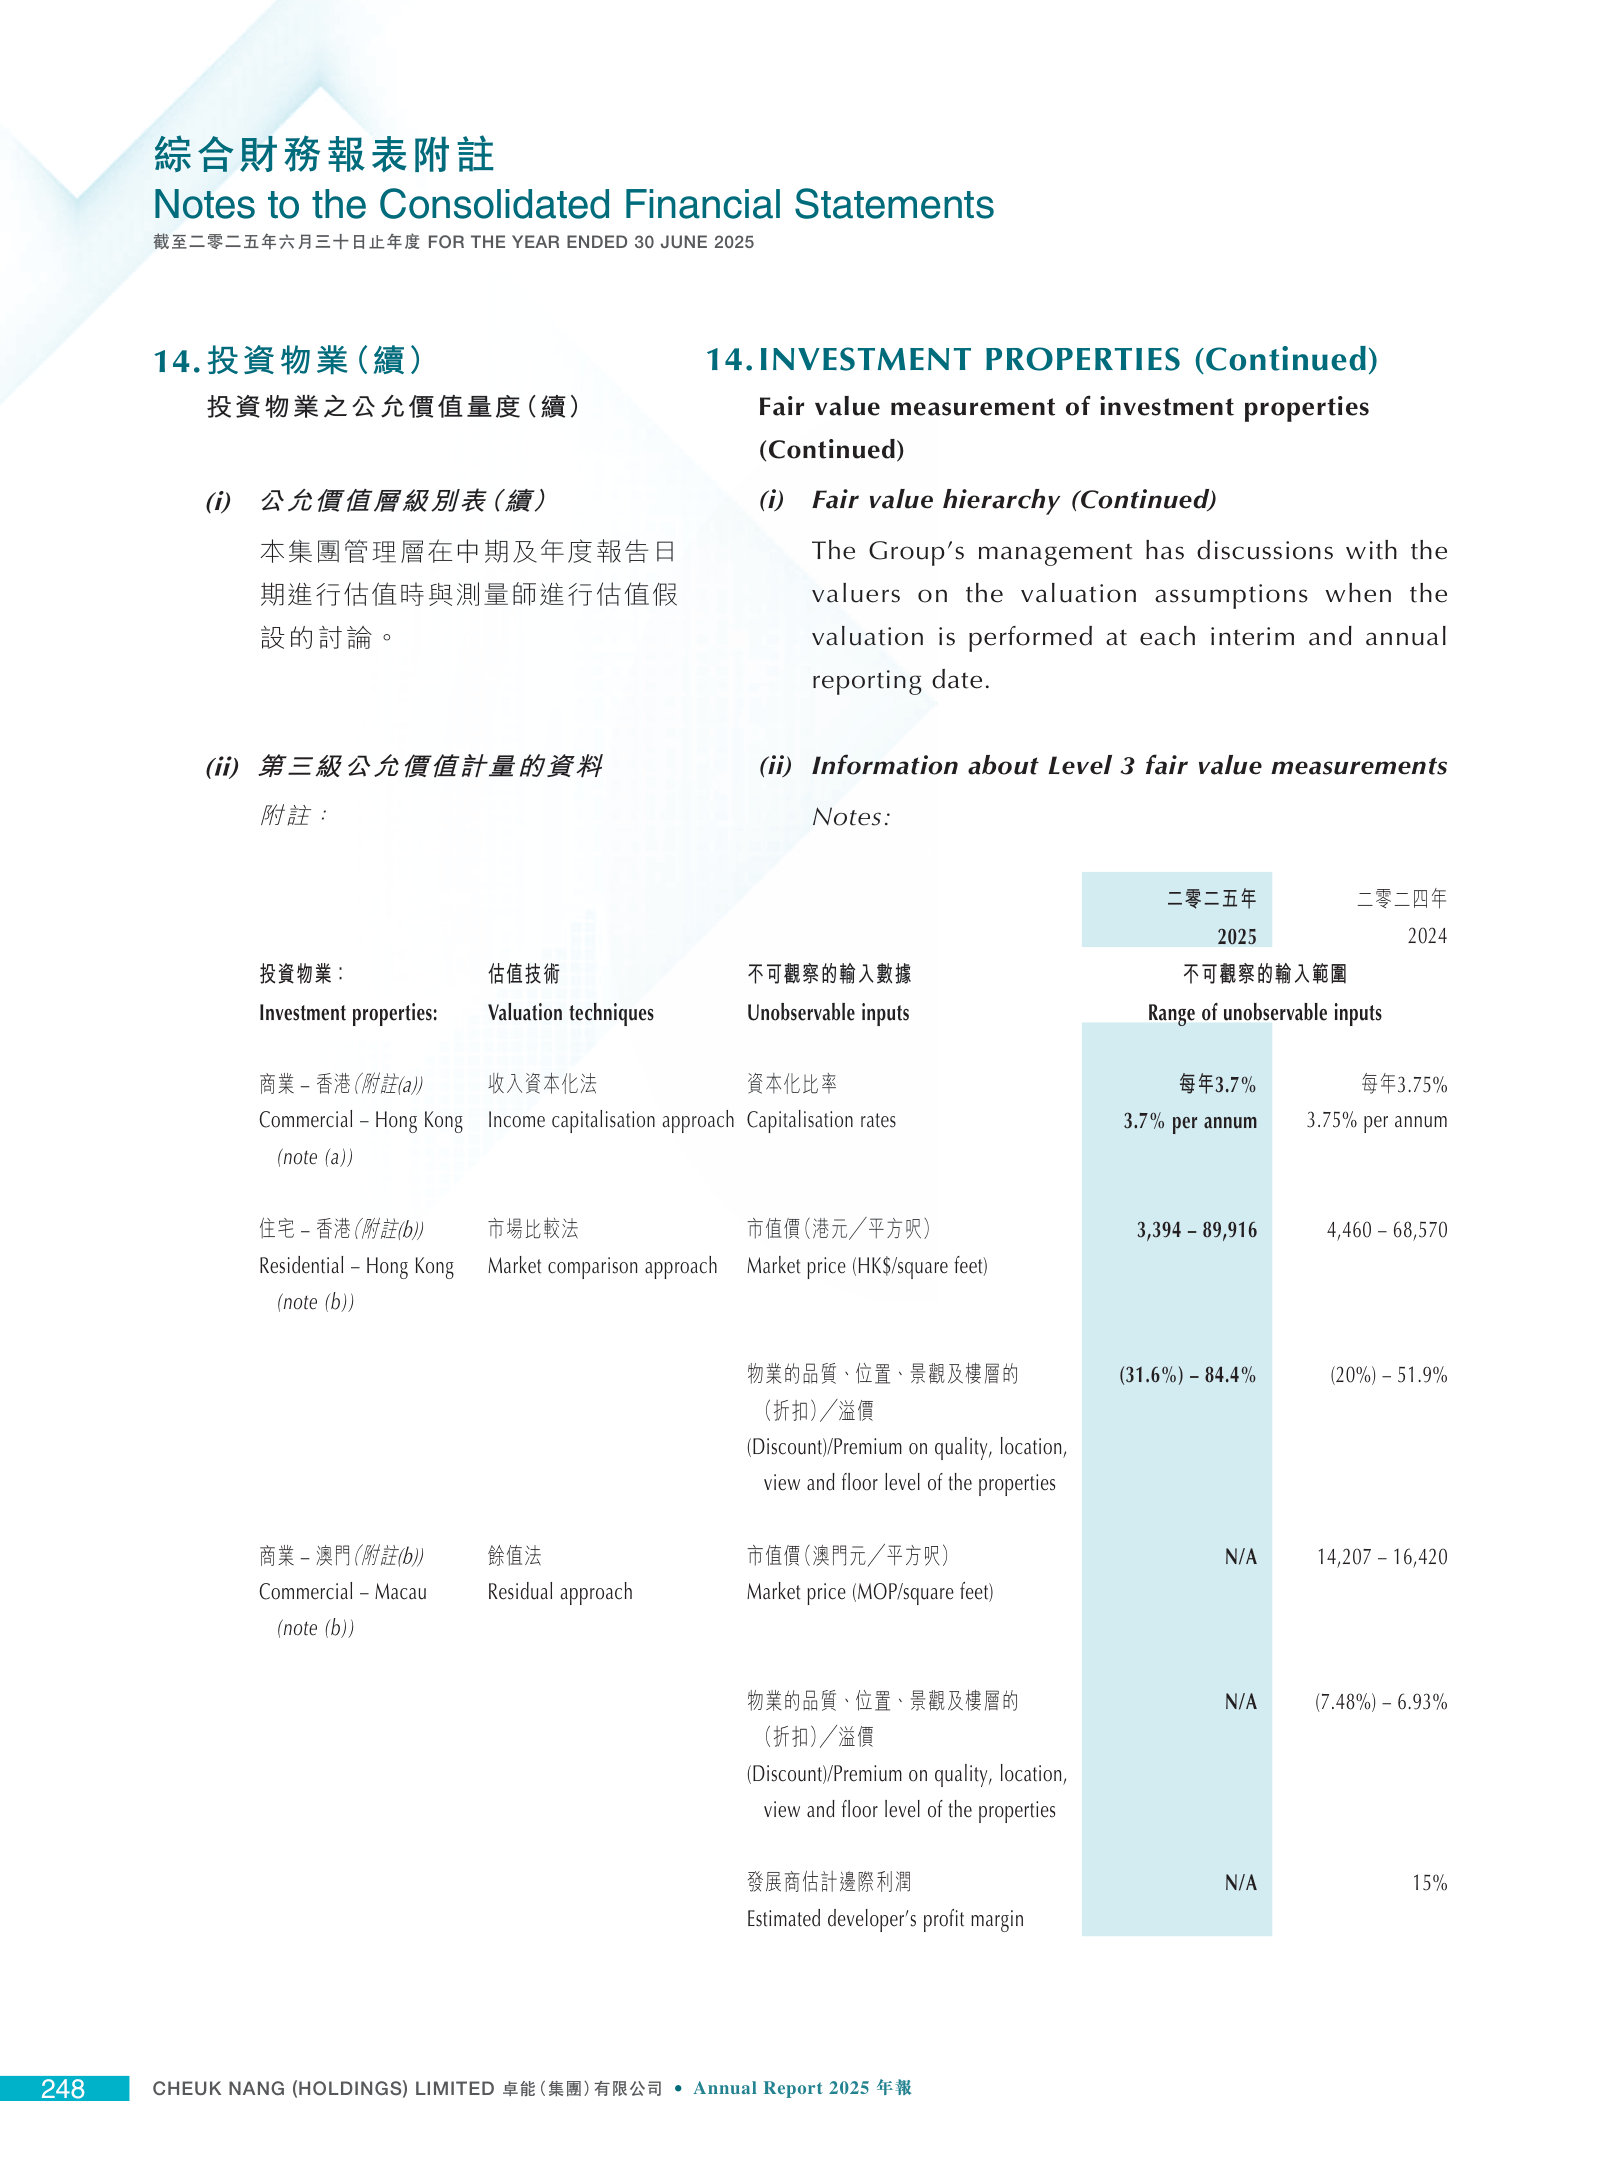
14. Investment Properties — p. 244 · Read the full section →
The roll-forward and the valuation inputs behind the year's largest number.
19. Properties Held for Sale — p. 265 · Read the full section →
Where the Macau project now sits, and the disclosure that its land lease renewal is still outstanding.
HK$166m written off development inventory; the Macau land lease renewal contract remains unobtained.
Provision for properties under development amounted to HK$166,068,000 (2024: HK$Nil) was recognised as an expense during the year ended 30 June 2025 and included in “administrative expenses” in the consolidated statement of profit or loss. […] The land lease renewal contract related to Macau land is yet to obtained as at 30 June 2025. The directors are of the opinion that the Group is entitled to lawfully and validly occupy and use the land, and therefore the aforesaid matter did not have any significant impact on the Group’s financial position as at 30 June 2025.
p. 265 · Read in context →
Cheuk Nang (Holdings) Limited — Annual Report 2024 (year ended 30 June 2024) — FY2024 (year ended 30 June 2024)
The prior edition, where Macau still sat in investment properties at HK$1,448m with its land-use application unresolved. · Open the full document →
Chairman's Statement — p. 12 · Read the full section →
The Macau account a year before the write-down: land-use consent withheld on two plots and the proposal sent back.
Macau: DSSCU consented to the land-use change except for plots A2 and B2, then asked for a re-submission.
The Direcção dos Serviços de Solos e Construção Urbana (DSSCU) has issued a proposal at the end of January 2024 consenting to the change of land use as applied by us with the exception of the land marked “A2” and “B2”. Objection has been made by our local lawyer to the DSSCU in March 2024 but the Government requested us to re-submit the development proposal.
p. 17 · Read in context →
More annual reports
Cheuk Nang (Holdings) Limited — Annual Report 2023 (year ended 30 June 2023) — FY2023 (year ended 30 June 2023) · 294 pages · The trough year: HK$45m of revenue and a HK$21m profit, with the dividend covered just 0.9 times. · Open →
Cheuk Nang (Holdings) Limited — Annual Report 2022 (year ended 30 June 2022) — FY2022 (year ended 30 June 2022) · 286 pages · A HK$149m loss on HK$57m of revenue; useful for seeing how often revaluations, not trading, set the result. · Open →
Cheuk Nang (Holdings) Limited — Annual Report 2021 (year ended 30 June 2021) — FY2021 (year ended 30 June 2021) · 294 pages · The last big sales year — HK$995m of revenue and HK$149m of profit — against HK$169m and a loss in FY2025. · Open →